Winning a manpower tender at the lowest price does not automatically mean winning a profitable contract.
One of the biggest mistakes a manpower contractor can make is calculating the tender rate using only:
Minimum Wage + EPF + ESIC + Service Charge
A real manpower contract can include many additional costs.
Depending on the tender, contractor and applicable law, the calculation may need to consider:
- Minimum wages
- Variable Dearness Allowance (VDA)
- EPF
- ESIC
- Bonus
- Gratuity
- Paid leave
- Weekly off
- Reliever manpower
- National / festival holidays
- Overtime
- Uniforms
- ID cards
- Police verification
- Supervisor cost
- Insurance
- Equipment
- Administrative expenses
- Bank guarantee cost
- Working capital
- Payment delays
- Service charge
- Profit margin
- GST
A manpower tender should therefore be treated as a complete contract-costing exercise.
This guide explains a practical method for calculating a sustainable manpower tender rate.
Basic Formula for Manpower Tender Rate
A practical manpower tender costing formula is:
Applicable Wage Cost
-
Employer Statutory Contributions
-
Employee Benefit Provisions
-
Operational Cost
-
Administrative Overheads
-
Financial / Working Capital Cost
-
Contract-Specific Cost
-
Risk Provision
-
Service Charge / Profit Margin
= Basic Tender Rate
Then apply GST or other taxes according to the tender's pricing structure and applicable law.
Minimum Wage Is Not the Final Tender Rate
Minimum wage represents only one component of manpower cost.
A contractor may still have to fund:
Minimum Wage
- Employer EPF
- Employer ESIC
- Bonus
- Gratuity
- Leave Cost
- Reliever Cost
- Uniform
- Administration
- Bank Guarantee
- Working Capital
- Service Charge / Profit
Therefore, quoting a tender only slightly above minimum wage can create a loss-making contract.
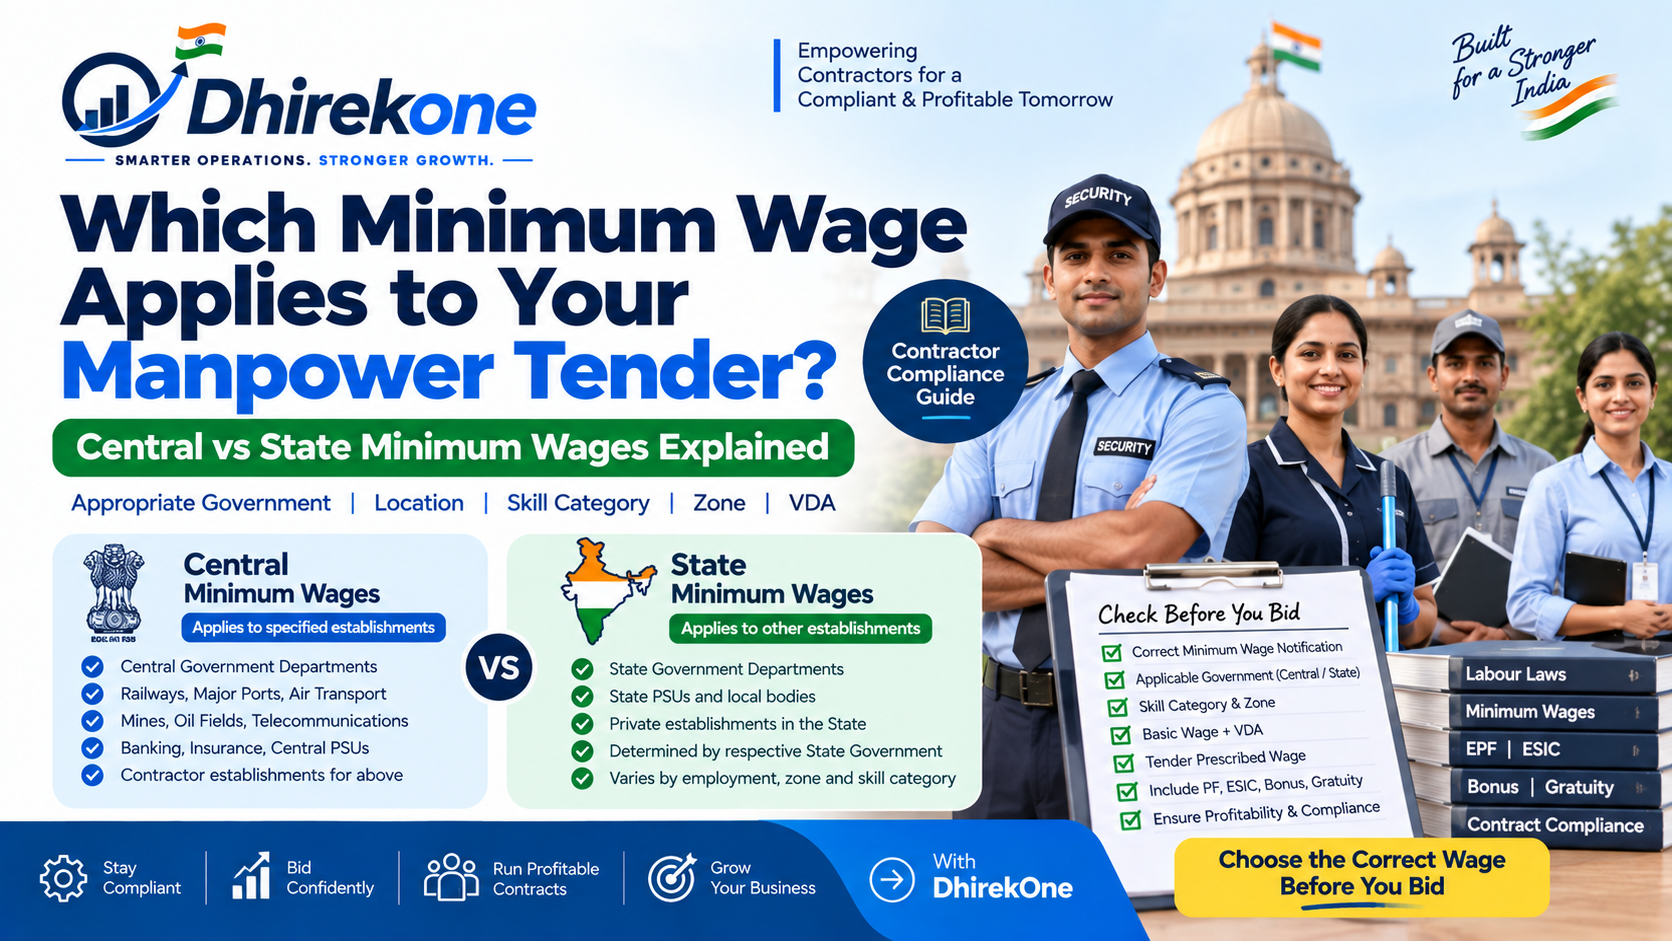
Step 1: Identify the Correct Minimum Wage
Start with the wage legally applicable to the manpower being deployed.
Check:
- Appropriate Government
- State / Central jurisdiction
- Employment / industry
- Skill category
- Zone / area classification
- Effective date
- Basic wage
- Variable Dearness Allowance
- Any special category requirement
Common skill categories may include:
- Unskilled
- Semi-Skilled
- Skilled
- Highly Skilled
Do not copy minimum wages from an old tender.
Minimum wages and VDA can change during a contract.
Central Minimum Wage or State Minimum Wage: Which One Should You Use?
The applicable wage depends on the appropriate Government and the legal and contractual context of the establishment or work.
A contractor should check:
- Who is the principal employer?
- Where will employees actually work?
- Which Government is the appropriate Government?
- What wage notification applies?
- What does the GeM bid specify?
- Has a higher wage been prescribed in the tender?
Where the tender itself requires a wage higher than the statutory minimum, the contractor should cost the tender using the applicable contractual requirement.
Never automatically use the lowest wage available.
Step 2: Convert Daily Minimum Wage to Monthly Wage
Many wage notifications specify wages on a daily basis.
Where the applicable tender / wage framework uses 26 payable working days for monthly conversion:
Monthly Wage = Daily Wage × 26
Example:
Daily Wage = ₹700
₹700 × 26 = ₹18,200 per month
However, always check the applicable notification and tender before applying a divisor or multiplier mechanically.
Step 3: Determine the Wage Structure
Identify how the statutory wage should be structured.
Depending on the applicable wage notification and payroll framework, the wage may contain components such as:
- Basic
- VDA / Dearness Allowance
- Other permitted components
Do not artificially split wages merely to reduce statutory contributions.
The wage definition under the current labour-code framework should also be considered while designing salary structures.
Step 4: Add Employer EPF Cost
Where EPF applies, include the employer's statutory contribution in your tender costing.
Do not confuse:
Employee PF Deduction
with
Employer PF Cost
The employee contribution is deducted from the employee's wage according to the applicable statutory framework.
The employer contribution represents an additional cost to the contractor and therefore needs to be considered separately in tender costing.
Also consider applicable:
- EPS allocation
- EDLI
- EPF administration charges
- Higher-wage contribution arrangements, where applicable
Employee PF Is Not an Employer Expense Twice
Be careful when creating your costing sheet.
Employee PF contribution:
- Is deducted from the employee's eligible wages
Employer PF contribution:
- Is an additional employer cost
Do not add the employee deduction again as an employer expense unless the tender specifically requires the contractor to bear it without deduction from wages.
Step 5: Add Employer ESIC Cost
Where ESIC applies, calculate the employer contribution on the statutory wage base applicable to that employee.
Keep separate:
Employee ESIC Contribution
and
Employer ESIC Contribution
The employee contribution is deducted from wages where applicable.
The employer contribution is an additional contract cost.
Step 6: Add Statutory Bonus Cost
Where statutory bonus applies, make an appropriate provision in the tender rate.
Do not wait until the end of the financial year to realise that the contract price did not include bonus cost.
Bonus costing should consider:
- Employee eligibility
- Applicable wage ceiling / calculation basis
- Applicable statutory minimum
- Contract requirement
- Contract duration
Treat bonus as a provision spread across the applicable contract period where appropriate.
Step 7: Add Gratuity Provision
Gratuity can create a substantial long-term contract liability.
Where gratuity liability may arise, include an appropriate provision in contract costing.
A frequently used actuarial-style monthly costing approach is based on the statutory gratuity relationship:
15 days' eligible wages ÷ 26 ÷ 12
This is approximately 4.81% of the applicable monthly gratuity wage base.
However, actual legal liability depends on employee eligibility, continuous service, applicable law, contract circumstances and the current labour-code framework.
Use this as a costing provision, not as an automatic statement that every employee must be paid 4.81% every month.
Provision Is Not the Same as Employee Deduction
Bonus and gratuity provisions are contract costs.
They should not automatically be treated as monthly deductions from the employee's salary.
A contractor's costing worksheet and an employee's payslip serve different purposes.
Step 8: Calculate Weekly-Off and Reliever Cost
This is one of the most frequently missed costs in manpower tenders.
Suppose the tender requires:
30 guards every day
and
each employee must receive a weekly off.
You may need additional manpower to maintain all 30 posts while regular employees take weekly rest.
Therefore:
Tender Headcount
may not equal
Actual Payroll Headcount
Your costing should determine:
Required Daily Posts + Reliever Requirement
Actual Deployment Strength
RELIEVER FORMULA
Simple Reliever Estimation
If each regular employee receives one weekly off after six working days:
Indicative Reliever Requirement:
Required Posts ÷ 6
Example:
30 Continuous Posts ÷ 6 = Approximately 5 additional reliever equivalents
Actual planning must also account for:
- Leave
- Absence
- National holidays
- Training
- Replacement delays
- Shift requirements
Therefore, actual reliever strength can be higher.
Step 9: Add Leave Cost
If employees are entitled to paid leave while the buyer still expects uninterrupted manpower deployment, the contractor may incur both:
Salary of employee on paid leave
Salary of replacement employee
Therefore, leave is not merely an HR issue.
It is a tender-cost component.
Review the tender and applicable law for:
- Earned leave
- Casual leave
- Sick leave
- Paid holidays
- Weekly rest
- Replacement manpower
Step 10: Check Overtime and Shift Requirements
Review:
- Daily working hours
- Weekly working hours
- Shift duration
- Night shifts
- Overtime requirement
- Holiday duty
- Extra deployment
Never calculate an 8-hour wage rate and use it for a tender that effectively requires 12-hour deployment without separately costing the additional lawful manpower or overtime requirement.
Do Not Convert an 8-Hour Wage Into a 12-Hour Duty Without Costing the Difference
If the tender requires round-the-clock or extended-hour operations, calculate manpower using legally compliant shifts.
For example:
One 24-hour post
does not mean
One employee working 24 hours.
Calculate the actual number of shifts and employees required to maintain the post legally and operationally.
Step 11: Add Uniform and Employee Onboarding Costs
Depending on the contract, include:
- Shirt
- Trousers
- Shoes
- Belt
- Cap
- Tie
- Jacket
- Safety equipment
- ID card
- Name badge
- Police verification
- Medical examination
- Training
- Joining documentation
Convert annual or one-time costs into a monthly cost per employee.
Example:
Annual Uniform Cost = ₹3,600
₹3,600 ÷ 12 = ₹300 per employee per month
Step 12: Add Supervisor and Management Cost
Some contracts require:
- Site supervisor
- Project manager
- Attendance coordinator
- HR support
- Payroll processing
- Compliance staff
- Billing staff
Even where these people are not billed directly as deployed manpower, their cost exists.
Allocate an appropriate portion of these expenses to the contract.
Step 13: Add Administrative Overheads
Administrative overheads can include:
- Payroll processing
- HR operations
- Recruitment
- Employee replacement
- Attendance management
- Compliance preparation
- Office expenses
- Software
- Accounting
- Audit
- Legal / professional fees
- Communication
- Tender preparation
- Travel
Ignoring overheads makes a contract appear more profitable than it actually is.
Step 14: Add EMD and ePBG Cost
Tender securities can affect your financing cost.
Consider:
- EMD
- Performance Security
- ePBG
- FDR blocking
- Bank Guarantee commission
- Cash margin
- Documentation charges
- Bank limits
Even if the principal amount is ultimately returned, blocked funds have an opportunity cost.What is EMD in a GeM tender?
Step 15: Calculate Working Capital Requirement
Manpower contracts are highly working-capital intensive.
The contractor may have to pay:
- Wages
- EPF
- ESIC
- Bonus provision
- GST
- Operational expenses
before receiving payment from the buyer.
Suppose:
Monthly Contract Cost = ₹10,00,000
Average payment cycle = 60 days
The contractor may need to finance approximately two months of operations:
₹10,00,000 × 2 = ₹20,00,000
This does not include security deposits or unexpected delays.
Therefore, the cost of working capital should be included when deciding the service charge and profit margin.
Step 16: Consider Payment Delay Risk
Government contracts may require:
Attendance certification → Wage payment → EPF / ESIC proof → Invoice submission → Verification → Payment processing
If any step is delayed, the contractor may have to continue financing payroll.
Before bidding, ask:
- Can the company finance two months of payroll?
- What about three months?
- What if the invoice is disputed?
- What if one compliance document is delayed?
A sustainable tender price should consider realistic cash-flow risk.
Step 17: Add Service Charge
Service charge is the contractor's commercial charge for organising and managing the service.
It may need to cover:
- Administration
- Recruitment
- Replacement
- HR
- Payroll
- Compliance
- Billing
- Management
- Financing
- Business risk
- Profit
Before entering a service charge on GeM, read the bid carefully.
The buyer or GeM service category may prescribe conditions relating to the permissible or minimum service charge.
Do not automatically use the service-charge percentage from another tender.
Service Charge Is Not the Same as Profit
A 5% service charge does not necessarily mean 5% net profit.
From that service charge the contractor may still need to pay:
- Staff salaries
- Office cost
- Recruitment cost
- Software
- Finance cost
- Bank charges
- Travel
- Employee replacement
- Tender expenses
- Compliance cost
Actual profit is what remains after all contract expenses are paid.
Step 18: Add Risk Provision
Every manpower contract carries operational risk.
Examples:
- Minimum wage revision
- VDA revision
- Employee absenteeism
- Sudden replacement
- Overtime
- Penalty
- Delayed payment
- Litigation
- Employee claims
- Additional statutory compliance
- Contract extension
- Wage revision during extension
Maintain a reasonable risk provision where the tender permits commercial pricing flexibility.
Step 19: Check GST Treatment
After determining the taxable contract value, check the applicable GST treatment.
Do not simply add GST to employee take-home salary.
Determine:
- Taxable value
- Whether quoted GeM price is GST inclusive or exclusive
- Applicable GST rate
- Reverse charge implications, if any
- Tender-specific tax instructions
The financial bid should follow the exact pricing structure prescribed by GeM and the buyer.
Manpower Tender Rate Calculation Formula
Monthly Cost Per Employee
A. Wage Cost Basic / Minimum Wage
- VDA = Gross Statutory Wage
B. Employer Statutory Cost
- Employer EPF
- Applicable EPF / EDLI / administrative cost
- Employer ESIC
- Bonus Provision
- Gratuity Provision
- Other applicable statutory benefits
C. Deployment Cost
- Weekly-Off / Reliever Cost
- Leave Provision
- Holiday / Replacement Provision
D. Employee Operating Cost
- Uniform
- ID Card
- Police Verification
- Training
- Insurance
- Equipment
E. Contract Overheads
- Supervisor Cost
- HR / Payroll
- Compliance
- Administration
- Banking Cost
- Working Capital Cost
- EMD / ePBG Cost
F. Commercial Cost
- Risk Provision
- Service Charge
- Profit Margin
= Basic Tender Rate
Then:
Basic Tender Rate
- Applicable GST = Final Tender Rate
Example: Manpower Tender Rate Calculation
Illustrative Example Only
Assume the following for one employee:
Monthly Applicable Wage = ₹20,000
Employer EPF Cost = ₹2,400 Employer ESIC Cost = ₹650 Bonus Provision = ₹1,000 Gratuity Provision = ₹962 Leave / Reliever Provision = ₹1,200 Uniform & Onboarding = ₹300 Administration = ₹600 Working Capital / Banking Cost = ₹300 Risk Provision = ₹300
Total Estimated Cost:
₹20,000
- ₹2,400
- ₹650
- ₹1,000
- ₹962
- ₹1,200
- ₹300
- ₹600
- ₹300
- ₹300
= ₹27,712
Assume Service Charge / Commercial Margin = ₹1,388
Basic Tender Rate:
₹27,712 + ₹1,388 = ₹29,100 per employee per month
GST should then be applied according to the applicable tender and tax treatment.
Important:
The numbers above are purely illustrative.
Do not use them as statutory rates for an actual tender.
How Government Organisations Cost Manpower
Government organisations themselves often build manpower estimates using multiple statutory and commercial components.
For example, a recent ESIC manpower cost estimate separately included:
- Monthly minimum wage
- Bonus
- Employer PF contribution
- Employer ESIC contribution
- Contractor profit / overhead
- GST
This demonstrates why minimum wage alone cannot be treated as the final manpower tender rate.
How to Calculate Rate for Multiple Manpower Categories
Never apply one average employee rate across all designations unless the bid expressly uses that structure.
Calculate separately for:
- Unskilled
- Semi-Skilled
- Skilled
- Highly Skilled
- Supervisor
- DEO
- MTS
- Security Guard
- Driver
- Accountant
- Technical manpower
Example:
Unskilled Rate × Quantity
Skilled Rate × Quantity
Supervisor Rate × Quantity
=
Total Monthly Manpower Cost
How to Calculate Annual Tender Value
Once the monthly contract cost is known:
Monthly Contract Rate × Contract Months
Base Contract Value
Then consider:
- Additional manpower
- Overtime
- Consumables
- Equipment
- Other billable components
- Applicable taxes
according to the bid structure.
Example:
Monthly Basic Contract Value = ₹8,00,000
Contract Duration = 12 Months
₹8,00,000 × 12 = ₹96,00,000
The final tender value may differ depending on GST and other components.
How to Calculate Manpower Tender Profitability
Do not measure profitability using only:
Tender Revenue - Salary
Use:
Total Contract Revenue
Employee Wage Cost
Employer Statutory Cost
Leave / Reliever Cost
Operational Cost
Administration
Finance Cost
Security Cost
Penalties / Risk
=
Actual Contract Contribution
Then deduct allocated company overheads to estimate actual profit.
Know Your Contract Profit Before You Bid
A manpower contractor should ideally know three numbers before submitting a bid:
- Statutory Minimum Cost
- Break-Even Contract Rate
- Target Bid Rate
If:
Bid Rate < Statutory Minimum Cost
the bid may be legally and commercially unsustainable.
If:
Bid Rate < Break-Even Cost
the contract can lose money even if salaries are paid correctly.
A contractor should bid only after understanding the complete contract economics.
Common Manpower Tender Costing Mistakes
Common mistakes include:
- Using outdated minimum wages
- Selecting the wrong skill category
- Ignoring VDA
- Ignoring employer EPF
- Ignoring employer ESIC
- Forgetting statutory bonus
- Forgetting gratuity provision
- Ignoring weekly-off relievers
- Ignoring paid leave
- Ignoring overtime
- Ignoring uniforms
- Ignoring police verification
- Ignoring supervisor cost
- Ignoring replacement manpower
- Ignoring bank guarantee charges
- Ignoring working capital
- Assuming service charge equals profit
- Ignoring payment delay
- Ignoring wage revisions during the contract
- Incorrect GST treatment
- Quoting simply to become L1
Why L1 Does Not Automatically Mean a Good Contract
Becoming the lowest bidder may help win a tender, but a contract awarded below sustainable cost can create serious problems.
A loss-making manpower contract can lead to:
- Delayed wages
- EPF / ESIC defaults
- Employee attrition
- Poor deployment
- Penalties
- Contract termination
- Working-capital stress
- Statutory claims
- Loss of Performance Security
- Business losses
The objective should therefore be:
Compliant Rate + Executable Rate + Sustainable Rate
not simply:
Lowest Possible Rate.
- Before submitting your financial bid, verify:
- ✅ Correct minimum wage notification
- ✅ Correct skill category
- ✅ Correct zone / location
- ✅ VDA included
- ✅ Wage revision risk considered
- ✅ Employer EPF included
- ✅ Employer ESIC included
- ✅ Bonus provision included
- ✅ Gratuity provision reviewed
- ✅ Weekly-off reliever included
- ✅ Leave cost included
- ✅ Overtime checked
- ✅ Holiday duties checked
- ✅ Uniform included
- ✅ ID / verification included
- ✅ Supervisor included
- ✅ Insurance checked
- ✅ Administrative overhead included
- ✅ EMD cost considered
- ✅ ePBG cost considered
- ✅ Bank charges included
- ✅ Working capital calculated
- ✅ Payment cycle reviewed
- ✅ Service charge checked
- ✅ Profit margin calculated
- ✅ GST treatment verified
- ✅ ATC reviewed
- ✅ Corrigendum checked
- ✅ Final contract profitability calculated
Calculate and Manage Manpower Contracts with DhirekOne
Manpower tender costing should not end with an Excel calculation.
After the contract is awarded, the assumptions used during bidding become actual operational costs.
The complete lifecycle becomes:
Tender → Rate Calculation → Bid → EMD → Award → ePBG → Contract → Site → Employee Deployment → Attendance → Payroll → Minimum Wages → EPF & ESIC → Compliance → Billing → Receivables → Contract Profitability
DhirekOne is designed to connect these workflows for manpower contractors, security agencies, housekeeping companies, facility-management providers and Government service contractors.
By connecting contract requirements with employees, attendance, payroll, statutory compliance, billing and receivables, contractors can compare expected tender economics with actual contract performance.
Frequently Asked Questions About Manpower Tender Rate Calculation
Q1. How do I calculate a manpower tender rate? Start with the applicable minimum wage, add employer statutory contributions, bonus and gratuity provisions where applicable, leave and reliever cost, operational expenses, administration, finance cost, service charge and profit. Apply GST according to the tender's pricing structure.
Q2. Is minimum wage the same as manpower tender rate? No. Minimum wage is only one component. The tender rate may also need to cover employer PF, ESIC, bonus, gratuity, leave, relievers, administration, financing and profit.
Q3. Should employer PF be included in a manpower tender? Yes, where EPF applies, the employer's statutory contribution represents an additional employment cost and should be considered when calculating the tender rate.
Q4. Should ESIC be included in tender costing? Yes, where ESIC applies. The employer contribution should be treated as an employer cost, while the employee contribution is handled through payroll according to applicable law.
Q5. Should bonus be included in the tender rate? Where statutory or contractual bonus liability applies, the contractor should make an appropriate provision while calculating the manpower rate.
Q6. Should gratuity be included in manpower costing? Where gratuity liability may arise, an appropriate provision should be considered so that future employee liabilities are not funded entirely from the contractor's profit.
Q7. What is reliever cost in a manpower tender? Reliever cost is the additional manpower cost required to maintain the contracted number of posts when regular employees are on weekly off, leave or otherwise unavailable.
Q8. Is service charge the contractor's profit? Not necessarily. Service charge may first need to cover administration, recruitment, compliance, financing, replacement and other overheads. Net profit is the amount remaining after all costs.
Q9. How do I calculate monthly manpower cost? Calculate the total monthly wage and employer statutory cost per employee, add deployment and overhead costs, multiply by the required number of employees and then add commercial margin according to the bid structure.
Q10. Should EMD and ePBG be included in tender costing? Their principal amounts may be refundable, but blocked funds, Bank Guarantee fees, FDR margins and financing costs can affect contract economics and should therefore be considered.
Q11. How do I calculate manpower contract profitability? Subtract wages, statutory contributions, employee benefits, reliever cost, operational expenses, administration, finance cost, security cost and other contract expenses from contract revenue.
Q12. Should I quote the lowest possible price to become L1? A bidder should ensure that the quoted rate satisfies statutory obligations and is operationally and commercially sustainable. Winning at a rate below true contract cost can create losses and compliance problems.
CONCLUSION
Conclusion
A manpower tender rate should never be calculated using minimum wages alone.
A sustainable rate should consider the complete cost of employing and deploying manpower, including applicable wages, EPF, ESIC, bonus, gratuity, leave, relievers, uniforms, supervision, administration, bank guarantees, working capital, service charge and profit.
The exact calculation will vary according to:
- State
- Appropriate Government
- Skill category
- Wage notification
- Employee salary
- Contract location
- Tender conditions
- Applicable labour law
- Deployment model
- Payment cycle
Before submitting a financial bid, contractors should calculate both the statutory minimum cost and the actual break-even cost of the contract.
The lowest quotation is useful only when the contract can still be executed compliantly and profitably.
DhirekOne helps Government contractors connect tender costing with contract execution, employee deployment, attendance, payroll, labour compliance, billing, receivables and profitability.